Quick answer: The Netherlands-USA DTAA (Double Taxation Agreement) is an income tax agreement between the Netherlands and the USA. It stops the same income from being taxed twice and sets the rules for taxing cross-border income. It was signed on 18 December 1992 and applies to tax residency, business profits, dividends, interest, and royalties. Depending on the type of income and the treaty conditions, eligible taxpayers may get reduced withholding tax rates or relief for foreign tax.
If you’re a Dutch resident with US income, an American living in the Netherlands, or a business operating in the Netherlands and USA, knowing how the US-Netherlands tax treaty works can make your tax obligations much clearer and help you avoid unnecessary costs. This guide walks through the treaty’s key provisions, withholding tax rates, who is eligible, and how to claim relief.
What Is the Netherlands-USA Double Taxation Avoidance Agreement (DTAA)?
The Netherlands-USA DTAA is a bilateral income tax treaty. It was signed in Washington on 18 December 1992 and, according to the US Treasury, entered into force in 1993. A protocol signed on 8 March 2004 updated it later. The protocol generally applies to taxable periods beginning on or after 1 January 2005, and its withholding tax rules took effect for payments made from 1 February 2005.
“DTAA” is the term used in India and several other countries for a double taxation avoidance agreement. In the Netherlands and the US, the same document is simply called the income tax treaty. Whatever you call it, it has two goals: preventing double taxation and preventing tax avoidance and evasion. It doesn’t create new taxes. Decide which country can tax a certain type of income and how the other country should provide relief.
How Does the US-Netherlands Tax Treaty Work?
The root of the problem is that the two countries tax on different bases. The U.S. taxes its citizens anywhere they live, while the Netherlands taxes principally based on residency. So a US citizen living in the Netherlands can end up inside both systems at once. The Dutch Tax Administration notes that such a person may have to file one tax return in the Netherlands and another in the United States.
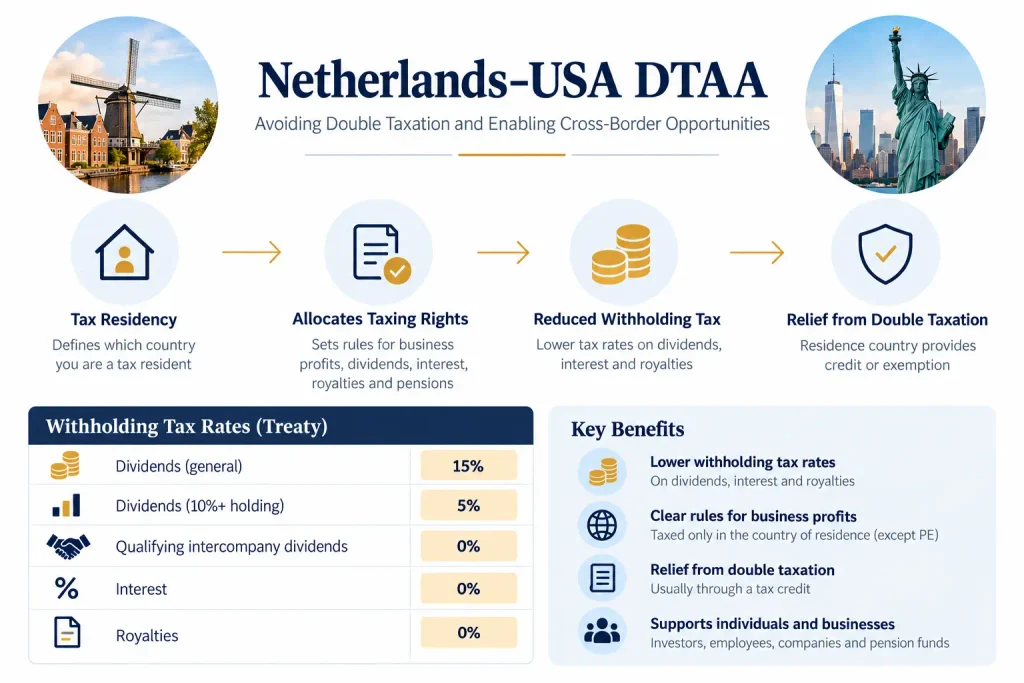
The treaty deals with this in three steps:
- It decides residency (Article 4): Where you are a resident in both countries, tie-breaker tests apply in the following order: permanent home, centre of vital interests, habitual abode, nationality and agreement of the tax administrations.
- It allocates taxing rights: business profits, dividends, interest, royalties, and pensions each follow their own rule, and the source country’s tax on passive income is capped.
- It requires relief: The country of residence must relieve double taxation on income that the other country is entitled to tax, usually through a credit.
One limit matters, especially for Americans. Under the savings clause in Article 24, the US keeps the right to tax its own citizens as if the treaty didn’t exist. That means being treated as a Dutch resident doesn’t end your US filing obligation, and US citizens get relief mainly through foreign tax credits.
What Are the Withholding Tax Rates Under the Netherlands-USA Tax Treaty?
Withholding tax is taken at source, before a dividend, interest payment, or royalty reaches the person receiving it. Without a treaty, US-source payments to non-residents generally face a 30% US withholding rate, and the Netherlands applies a 15% dividend withholding tax on distributions by Dutch companies. The treaty brings these rates down:
| Income type | Treaty rate | Article |
|---|---|---|
| Dividends (general) | 15% | 10 |
| Dividends to a company holding 10%+ of voting stock | 5% | 10 |
| Qualifying intercompany dividends | 0% | 10 (2004 protocol) |
| Interest | 0% | 12 |
| Royalties | 0% | 13 |
The 0% dividend rate was introduced by the 2004 protocol, which eliminated source-country withholding tax on certain intercompany dividends. Coverage of the protocol describes the main case as a publicly traded company that has directly owned at least 80% of the payer’s voting stock for the previous 12 months.
Keep in mind that these rates don’t apply automatically. The recipient must be the beneficial owner and a treaty resident, and companies also have to meet the Limitation on Benefits (LOB) rules in Article 26. Before relying on any rate, check the current conditions in the official treaty text.
How Does the Tax Treaty Apply to Business Profits?
Under the Netherlands-USA DTAA, a company’s business profits are generally taxable only in the country where it is resident. The exception is a permanent establishment (PE). If a Dutch company does business in the US through a PE, the US may tax the profits attributable to it, and the same holds in reverse for US companies operating in the Netherlands. These rules sit mainly in Articles 5 and 7.
A PE usually means a fixed place of business, such as an office, branch, factory or workshop. A long-running construction project can qualify, and so can a dependent agent who regularly concludes contracts on the company’s behalf. Advisers also point out that data centres, storage and distribution facilities, pop-up stores and online business operations can raise PE questions, depending on the conditions.
For Dutch companies selling into the US, the practical move is to run a PE check before staff travel, warehouses open, or agents are appointed. If there’s no PE, the treaty generally keeps business profits taxable only in the Netherlands. If there is one, the Netherlands must relieve the US tax on those profits.
How Does the Netherlands-USA DTAA Prevent Double Taxation?
The treaty prevents double taxation mainly through Article 25, which requires each country to relieve double taxation on income the other country is allowed to tax. Two methods exist in treaty practice. With the credit method, the country of residence taxes worldwide income but credits the tax already paid abroad. With the exemption method, it simply exempts the foreign income. The US uses the credit method for its citizens and residents, typically through Form 1116, and the Dutch Tax Administration confirms that the US will usually set off the tax paid in the Netherlands against US tax on the same income.
The two systems don’t always line up neatly. The Tax Administration gives examples where the Netherlands grants an exemption, but the US still taxes the income, or where the Netherlands doesn’t treat an amount as income, but the US does. In those cases, the final tax bill can differ from what you expected, which is why planning matters.
For a Dutch resident with US dividends, the sequence is straightforward: claim the reduced treaty rate at source, then claim relief for the US tax in your Dutch return. And if the two tax authorities read the treaty differently, the mutual agreement procedure lets them settle the dispute between themselves.
Who Can Benefit From the US-Netherlands Tax Treaty?
- Dutch residents with US income: Investors, freelancers, and employees who receive US dividends, interest, or royalties can use the reduced withholding rates and then claim relief at home.
- US citizens and green card holders in the Netherlands: They get clarity on who taxes what, plus relief through credits, although the savings clause means they still file in the US. They should also know that financial institutions worldwide must pass US citizens’ financial data to the IRS under FATCA, so reporting can’t be avoided.
- Dutch companies with US subsidiaries or customers: They benefit from the PE rules and from low or zero withholding on dividends, interest, and royalties.
- US companies investing in the Netherlands: Those that qualify can reduce Dutch dividend withholding tax.
- Pension funds: The competent authorities of both countries settled a mutual agreement that changes how US pension funds obtain an exemption from Dutch dividend withholding tax, so funds should check the current procedure.
How Can You Claim Benefits Under the Netherlands-USA Tax Treaty?
- Confirm your residency: Get a residency certificate from your tax authority.
- Check your eligibility: Companies should test LOB and beneficial ownership before assuming a reduced rate.
- Submit the right form: For US-source income, individuals give the US payer Form W-8BEN, and entities give Form W-8BEN-E. For Dutch-source dividends, the Dutch payer applies its own relief procedure.
- Keep records of the tax paid in both countries.
- Claim relief in your return: Dutch residents do this in the Dutch return, and US citizens use Form 1116.
Two things to watch in 2026. First, treaty benefits aren’t automatic, so documentation and substance matter. Second, the Netherlands implements a conditional withholding tax, which is applied to dividends, interest, and royalties paid to affiliated companies in specified low-tax jurisdictions or in certain abuse cases.
The rate for 2026 is 25.8%, which a tax treaty may reduce. Genuine payments between Dutch and US companies are normally outside its scope, but holding structures still deserve a review. Large groups should also keep Pillar Two in mind, since the Dutch tax authorities issued an updated Pillar Two Q&A on 16 June 2026.
Conclusion
The Netherlands-USA DTAA gives you a framework for managing cross-border taxation, with rules for business profits, dividends, interest, royalties, and relief from double taxation. That said, treaty benefits depend on your tax residency, the type of income, and the eligibility requirements. US citizens living in the Netherlands should also remember that their US tax obligations may continue even when they qualify as Dutch residents.
If you’re planning to set up a company in the Netherlands or expand your business into the US, understanding the relevant treaty provisions is an important first step. Contact OnDemand International for guidance on Dutch company formation and international business expansion, so you can plan your next steps with confidence.
FAQs
What is the Netherlands-USA DTAA?
It is an income tax agreement between the Netherlands and the USA. It divides taxing rights and requires relief, so the same income isn’t fully taxed twice.
When did the US-Netherlands tax treaty enter into force?
The treaty was signed on 18 December 1992 and entered into force in 1993. A 2004 protocol updated it and generally applies from 2005.
What is the dividend withholding rate under the treaty?
It’s generally 15%, or 5% for companies holding at least 10% of the voting stock. A 0% rate applies to qualifying intercompany dividends that meet the holding period and LOB tests.
Do US citizens in the Netherlands pay tax twice?
They file in both countries, but foreign tax credits normally reduce or remove the double tax. Differences between the two systems can still leave some tax payable.